Zero-based budgeting means assigning your available income to spending, saving and other planned uses until nothing is left unassigned. Some people call it a zero balance budget, but the balance that reaches zero is the plan, not your bank account. It does not mean spending every dollar. Money reserved for a future bill still has a purpose.
The method can be useful when you know what you earn but cannot explain where it goes. This guide shows how to build a personal monthly plan, correct it when costs change and check whether the money will be available when bills arrive. Examples use US dollars; readers elsewhere can substitute their currency and local costs. If you have never made a budget before, start with how to make a budget and come back to this method once you have a first plan.
What is a zero-based budget?
A zero-based budget is a plan for one month or pay period in which every dollar of take-home pay has a job. In a personal zero-based budget, income minus all planned allocations equals zero. Those allocations include money you intend to keep, not just purchases. This matches the method described in Ramsey’s explanation of a zero-based budget. Its budgeting product is not required to follow the approach.
Available income − spending − savings − other reserved amounts = $0 unassigned.
A bank balance answers “How much is in this account?” A budget answers “What is that money for?” A $700 balance may already include $500 for rent and $200 for groceries. Treating the full $700 as free to spend would ignore those commitments.
This article concerns household budgeting, not the business process of evaluating each department’s budget from scratch.
How to make a zero-based budget
1. Choose a period and identify spendable income
Start with one month or one pay period. Use take-home pay rather than salary before deductions. Keep existing savings separate unless you deliberately plan a withdrawal: carrying the same savings into every month’s income would repeatedly allocate the same money.
For your first plan, gather pay records and recent bills. The FTC’s consumer.gov budgeting guide recommends using those records to compare income with expenses. Its fillable budget worksheet includes both after-tax wages and savings deposits.
2. Give the money specific destinations
List housing, utilities, food, transport and other commitments before optional purchases. Include the actual required payments for your circumstances. Then add savings goals and foreseeable costs that do not occur every month.
Suppose an annual subscription costs $120 and is due in 12 months. Reserving $10 each month would cover that amount if all 12 contributions are made. If it is due in three months and nothing is reserved yet, the same target requires $40 per month. Use the time remaining, not an automatic division by 12.
For several upcoming bills, use the sinking funds calculator to work out a monthly set-aside from each bill’s cost, existing reserve and time remaining. Enter those amounts in your budget once; moving reserved money between your own accounts is not a second allocation.
3. Allocate the remainder or address the shortfall
Add every destination and subtract the total from income. A positive number is still unassigned. You can reserve it for a goal, a coming bill or a clearly named buffer. A negative number means the proposed plan needs more money than you have; adding a negative “savings” line does not fix it.
If essential costs alone exceed income, a budgeting method cannot make that gap disappear. Identify the shortfall and explore realistic changes or local assistance. Do not cut necessities just to make the worksheet appear balanced.
Zero-based budget example: $3,000 a month
This is an invented teaching example, not a recommended allocation or a claim about typical US living costs. The household has $3,000 available for the month, no extra income assumed and these planned destinations:
| Destination | Amount |
|---|---|
| Rent | $1,100 |
| Utilities and phone | $220 |
| Groceries and household supplies | $400 |
| Transport | $250 |
| Insurance and health costs | $180 |
| Required debt payments | $150 |
| Emergency savings | $250 |
| Annual-bill reserve | $100 |
| Personal and leisure spending | $200 |
| Unplanned-cost buffer | $150 |
| Total allocated | $3,000 |
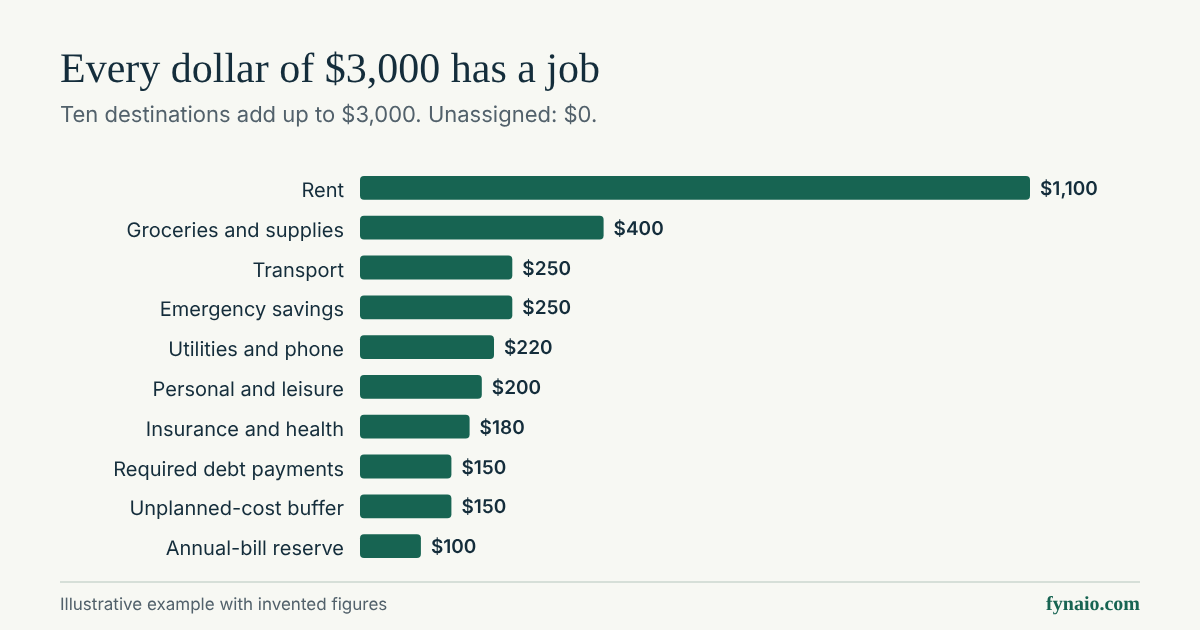
The household plans $2,650 for current spending and a buffer, plus $350 for emergency savings and future bills. Nothing is unassigned, yet $350 is deliberately kept for later. The buffer is also reserved until needed; it is not a target to spend.
Now suppose groceries cost $460 rather than $400. The household can reduce its unused buffer from $150 to $90. The extra $60 is accounted for and the total remains $3,000. This works only if that $60 is genuinely available, not already spent or needed elsewhere.
A balanced month can still run short before payday
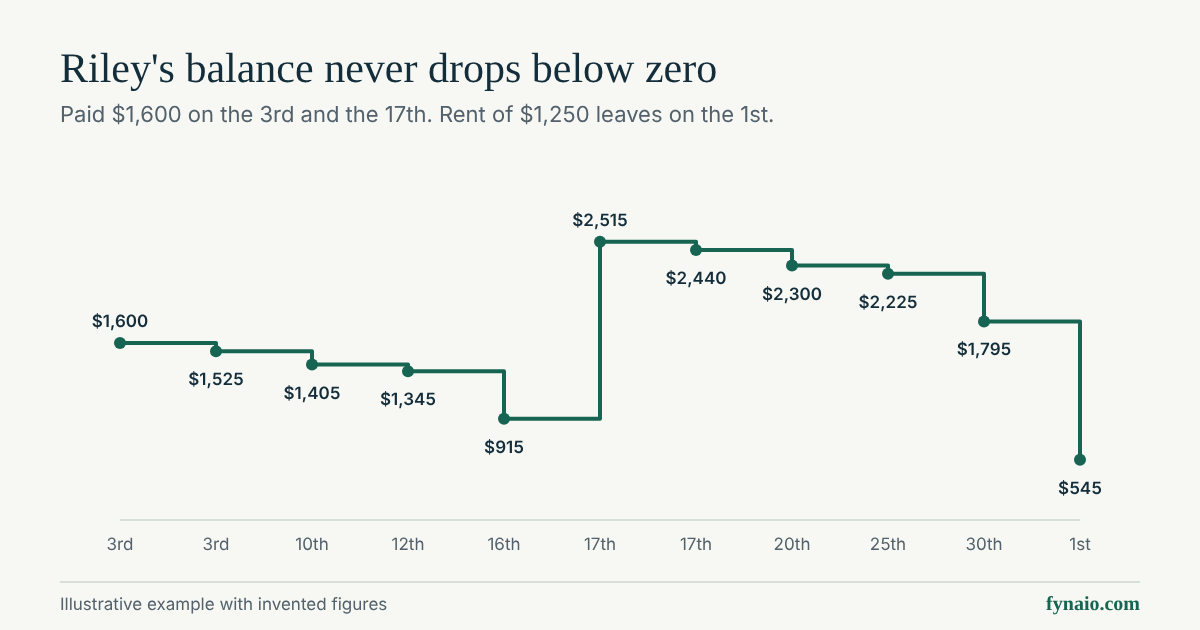
Allocation and timing are different checks. Imagine the example household receives $1,500 on the first day and $1,500 halfway through the month. Rent of $1,100 and utilities of $220 are due before the second paycheck. That leaves only $180 from the first paycheck for other early-month costs, even though the full month balances.
The CFPB’s cash-flow budgeting tool addresses this timing problem by comparing weekly starting balances, money coming in and money going out. Put due dates beside your allocations and check each period separately.
In this scenario, the household would need to adjust timing where possible or identify money already available to cover the gap. Moving figures on a spreadsheet cannot make a future paycheck arrive earlier.
What if your income changes every month?
A forecast is useful for seeing what may be possible, but distinguish it from money available now. If freelance payments arrive unpredictably, a monthly forecast of $3,000 is not permission to spend $3,000 before it arrives.
One practical approach is to allocate each received payment against the next commitments first, then update the wider monthly plan. Keep a separate list of costs not yet covered. If more income arrives, assign it then; if it does not, the uncovered costs remain visible rather than hidden inside an optimistic estimate.
For self-employed readers, not every payment received is personal spending money. Business costs and local obligations need separate consideration. This guide does not calculate those obligations or provide tax advice.
Zero-based budgeting or the 50/30/20 rule?
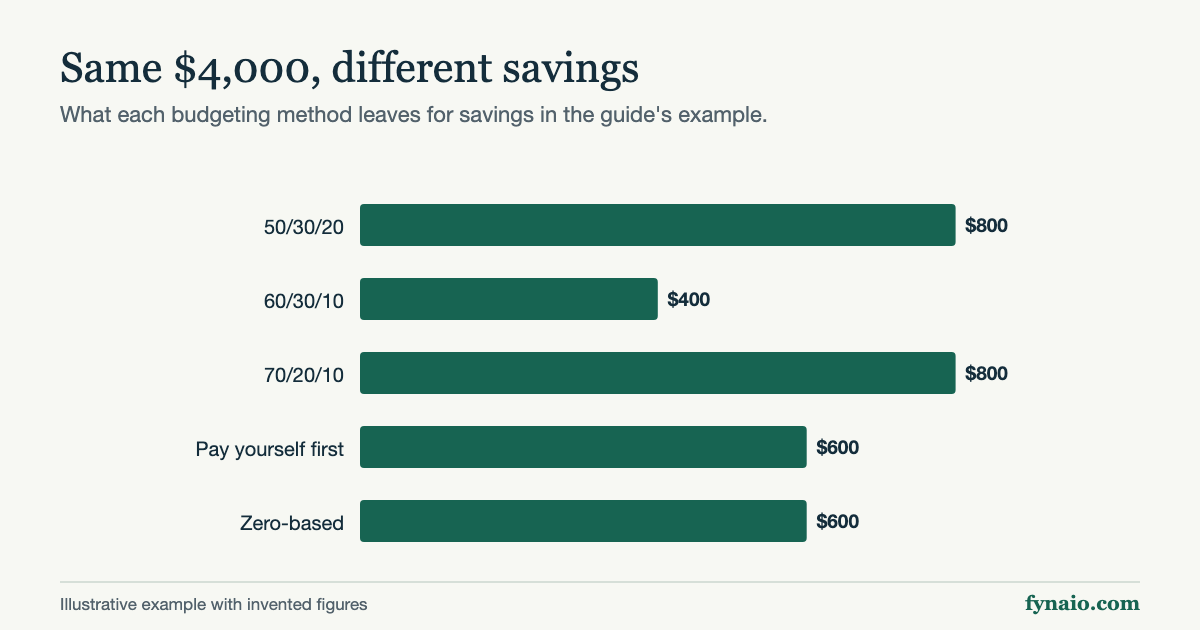
Zero-based budgeting names individual destinations. The 50/30/20 framework starts with three broad buckets: needs, wants and saving goals. Our 50/30/20 budget planner can help you explore that simpler starting split, but it is not a zero-based budgeting calculator.
You can use broad buckets for orientation and then assign the amounts to specific costs. Do not force your rent or grocery costs into a percentage that does not fit. If a detailed plan feels burdensome and your bills are already covered reliably, a simpler system may be easier to maintain.
Zero-based budget template
Copy this worksheet into a notebook or spreadsheet. Add the categories you actually need rather than copying every category in the example.
- Period covered: ______
- Income available for this plan: ______
- Required bills and due dates: ______
- Everyday spending: ______
- Savings and future-bill reserves: ______
- Named buffer: ______
- Total allocated: ______
- Available income minus total allocated: ______
Setting it up as a spreadsheet
In Excel, Google Sheets, LibreOffice or Numbers, put your income in cell B1. List one destination per row from row 4 down, with these columns:
- Column A: destination, such as rent or emergency savings.
- Column B: due date, so you can check payday timing.
- Column C: planned amount.
- Column D: used so far.
- Column E: remaining, with the formula
=C4-D4copied down.
In cell B2, enter =B1-SUM(C4:C13) for ten destination rows, and extend the range if you add rows. B2 shows what is still unassigned. The plan is zero-based when B2 shows 0. With the $3,000 example above in rows 4 to 13, B2 shows 0. If groceries rise to $460 and nothing else changes, B2 shows −60 until you reduce another line, such as the buffer, by $60.
Alongside each destination, keep “planned,” “used” and “remaining” columns. A reserve carried forward is not new income. If you move $40 between categories, reduce one allocation and increase the other by $40 so the total stays unchanged.
To skip the setup, download the zero-based budget spreadsheet with the $3,000 example already in place. It opens in Excel, Google Sheets or LibreOffice with the formulas above, plus a payday check at the bottom: it adds up everything due on days 1 to 14 ($1,320 for rent and utilities) and subtracts it from a $1,500 first paycheck, showing the $180 left for other early-month costs. Replace the example amounts, due days and paycheck with your own; costs marked weekly are left out of the check, so count the first weeks of those yourself.
For fixed categories instead, the monthly budget template lets you enter amounts on screen and download a spreadsheet with working totals. For this method, assign any positive remainder to a named purpose until the plan reaches zero.
Keep transfers and carried-forward savings from being counted twice
Your budget categories and bank accounts are different views of the same money. Moving $250 from checking to savings changes its location, not your total income. If you already assigned $250 to emergency savings, do not record the transfer as another $250 of spending in the allocation plan.
Likewise, when you reserve $100 this month for an annual bill, that $100 remains assigned next month until you use or reassign it. Keep a separate reserve balance rather than adding the same money to each month’s new income. When the bill arrives, draw from that reserve; include only any additional amount still needed in the current month’s allocations.
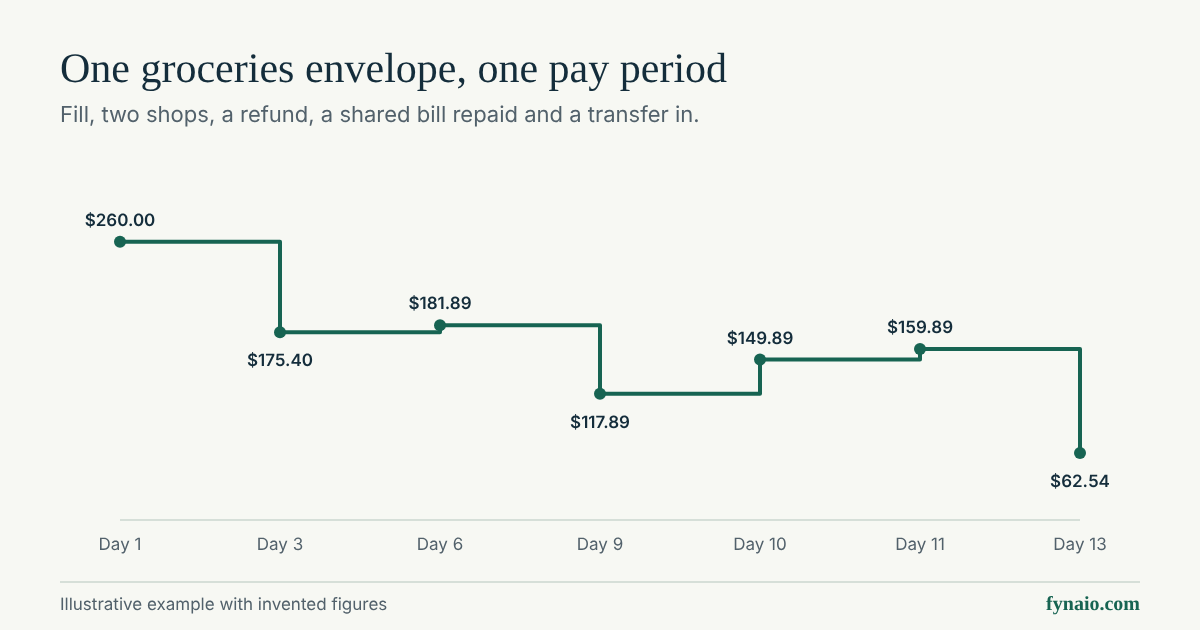
For purchases paid by card, choose one consistent tracking method. If your spending log already records the purchases against groceries or transport, a later payment covering those purchases must not allocate the same money again. Older balances and their required payments need a separate line. Do not remove a real payment from the payday-timing check just because it is not a new purchase.
- Compare your spending log with actual account transactions, including pending payments.
- Identify transfers, existing reserves and payments for purchases already counted.
- Correct duplicates and reassign only money that remains genuinely available.
- Recheck both the allocation total and the money available before each due date.
Common questions
Should my bank account reach zero?
No. Zero refers to unassigned money in the plan. Savings, upcoming bills and buffers may all remain in your accounts. The method does not require draining an account.
What happens to unused grocery money?
Choose its next purpose: keep it available for groceries, reserve it for another goal or move it to a different category. Record the decision and avoid counting it again as next month’s new earnings.
Is this the Dave Ramsey zero-based budget?
Ramsey Solutions teaches the zero-based budget and offers its own budgeting app, but the method does not depend on any product and needs only a worksheet. The steps on this page work on paper or in any spreadsheet.
Do I need a budgeting app?
No. A worksheet is enough to make the allocation. An app may make tracking easier, but check its cost and data access before choosing one. This guide does not endorse a provider.
Your first-month check
Before using the plan, check that every allocation has a purpose, that the arithmetic balances and that early bills do not depend on later income. After a week, compare the plan with actual transactions. Adjust the amounts instead of treating the first estimate as a test you must pass.
The useful outcome is a clearer view of what your money needs to do, not a perfect-looking spreadsheet. Start with accurate figures, leave room to revise them and keep saved money visibly separate from money free to spend.